From Daily Briefing
Medicare claims hammer Humana
Another HMO has hit the wall. Humana (HUM) on Wednesday became the second big health insurer this week to warn Wall Street about sharply lower-than-expected earnings. The Louisville, Ky.-based company said it expects to make 44 to 46 cents a share for the first quarter, down from its previous guidance of 80 to 85 cents a share. Humana expects to make $4 to $4.25 a share for the year, below its earlier projection of $5.35 to $5.55.
Unlike WellPoint (WLP), whose shares plunged Tuesday after the insurer warned of rising claims expense, Humana is blaming higher-than-expected claims on its Medicare Part D business. But the weak forecast from Humana could lead to more selling in names like Aetna (AET), which saw its shares drop 10% yesterday even after the company reaffirmed its own earnings guidance. Suddenly the health insurance stocks aren’t looking like such a good hedge play in a weakening economy.
Wednesday, March 12, 2008


Costco Update
From Mike Goodsen
On February 27th of this year, Goldman Sachs downgraded its rating on Costco (COST) to "neutral" from "buy." Whenever I see downgrades like this based on concerns of valuation (and if the stock isn't hitting new 52-lows -- something that too often accompanies sell-side downgrades), my contrarian spidey sense begins to tingle. When I see that most analysts rate the shares hold and only a few brave souls continue to recommend this stock, I want to know more. (Aside -- in my experience valuation alone is rarely a reason for a stock to go up or down. High expectation stocks which carry a premium valuation may be vulnerable to negative surprises, but absent a "problem," premiums can persist for a long time. Ditto for some cheap stocks and their low valuations.) It seems that COST is a stock everyone would love to love but the perceived high P/E is keeping analysts on the sidelines. Yet the lowest target price I could find was $60 -- right about where the stock is now.
The shares are now trading at 20.4x the '08 EPS consensus estimate of $2.98 and 17.7x the '09 EPS estimate. Most agree that the stock's recent P/E range is around 20-23x. According to my calculations, the stock has reached as high as 25x on in the recent past. Given this history, one could argue that the shares are "cheap" at $60. One could infer price targets of $68.54 (23x '08) and $78.89 (23x '09) simply using historical average P/Es. Interestingly, the sell-side consensus target price is the just below the mid-point of these numbers = $71. Although the consensus recommendation is "hold," the consensus target price implies upside of 17% from the current level. Not bad for a stock few seem to like. Yes, but what about the recession? Costco is a retailer after all and in a recession all retailers suffer, right? Well, looking back at the last recession (2000-2001), the shares traded as low as 18.9x (around $28) in 2002. Hmm, doesn't sound like disaster does it? What about the earnings expectations? Yes, there could be some slippage here, but why would all the analysts who rate the shares "hold" have unreasonably high EPS estimates? It seems to me that the shares could already be near a bottom even if a recession is around the corner.
Operationally, the company seems to march along with little regard to the economy. The company currently operates 529 stores, having opened up about 30 new stores in 2007. In 2008, it plans to open about 30 new stores again. I suspect management reads the newspaper and is aware of what's going on in economy, but unlike many investors, the folks who run COST are not becoming more defensive just because the economic outlook is weakening. Some suggest that Costco's average shopper is more affluent than the average consumer and is likely to be less affected by the recession, if and when it comes. If this is true, it might be another positive to the story.
The historical 5-yr EPS CAGR (compound annual growth rate) is around 12% and the consensus future EPS expected growth is 13.6%. Why would anyone pay 20x for a stock growing earnings at 13-14%? I can see two reasons: 1) earnings consistency and 2) higher earnings potential. If one looks back at the last 12 quarters, the company has not logged a negative earnings surprise. To me, this suggests the company has a very tight handle on its costs and revenues. The fact that management opens up the same amount of stores each year suggests they know where the new demand will be and are placing stores accordingly.
Some analysts suggest that the company could earn much more than they do, if they chose to do so. COST's gross margin is only 12.4% vs. Wal-Mart's 23.5% and Target's 32.6%. Operating margins for the three firms are 2.6%, 5.8% and 7.3%, respectively. Granted, the store business models are not exactly the same, but it seems to me that COST could see some meaningful margin expansion if it wanted. It appears that the company is happy to "give away" some of its margin to employees and customers -- not really a bad strategy in my view.
These factors may account for the higher-than-expected multiple. After looking at the stock , I ended up buying the shares on February 27, the day of the Goldman Sachs downgrade and sold the April $62.50 calls against my position, netting me a cost of $60.21. I can see the stock easily reaching the consensus target of $71 over the next 12 months or so and would not be surprised to see the shares in the $75-79 sometime next year. Although COST may not look like a typical "value" stock here, I perceive great value for the patient long-term investor.
Tuesday, March 11, 2008
Exxon Pumped Up
From Alpha
Exxon Mobil to Increase Spending on Exploration
As oil prices rise, so does Exxon's budget.
Exxon Mobil (XOM), the world's most profitable oil company, has plans to grow and increase the amount of oil it is capable of pumping. Spending this year on exploration, production platforms and other so-called upstream operations will rise by about 21 percent to $19 billion, Tillerson said. The company will start 19 projects by the end of 2010 that will add the equivalent of 725,000 barrels of oil, enough to supply 10 percent of the refineries along the U.S. Gulf Coast.
The idea is that, since oil prices are on the rise, profits will increase. Indeed, despite the rising costs of pumping oil (Bloomberg reports that it cost $7.14 in 2007 for Exxon to pump a barrel of oil from the ground -- up from 2006's $6.04) Exxon continues to make plenty of money. The increased cost means that budget increases have to be made. Exxon, of course, chooses to spend the money on increased exploration and production, as well as increasing its liquefied natural gas operations.
While some environmentalists and environmentally friendly investors may decry Exxon's disregard for investment in alternative energy sources, there is no denying that Exxon's business model has worked very well in the past, and that its focus on fossil fuels continues to serve it well. Rising oil prices only help the cause. According to Bloomberg, every time oil prices by $1 per barrel, Exxon gets another $400 million in each year's after-tax revenue.
The Fed Pumps More Liquidity
From CNBC
The Federal Reserve announced a series of coordinated actions with other central banks to help ease liquidity pressures in funding markets.
The Fed will expand its securities lending program to loan up to $200 billion of Treasury securities under a new Term Securities Lending Facility (TSLF). It will lend the Treasuries for 28 days rather than the overnight loans of the existing program.
It will also increase its currency swap lines with the European Central Bank and the Swiss National Bank. The ECB swap agreement will increase up to $30 billion from the current $10 billion and the Swiss agreement to $6 billion from the current $2 billion. The increases will be in place through September of this year.
The TSLF, similar to the Term Auction Facility for cash loans, will also operate under an auction format and accept agency debt, agency mortgage-related debt.
The Fed move in essences broadens the type of assets it is willing to take as collateral from banks and expands the period of time it is willing to hold them.
The class of assets now includes mortgages and mortgage-backed paper, but only AAA-rated securities. What was once an overnight arrangement is now extended to 28 days.
In a related move, the Fed raised the amount of money available for its existing currency swap operations with other central banks, most notably the European Central Bank. The move, for instance, gives the ECB more dollars to work with financial institutions in its area of operations that might want to convert Euro-dominated financial instruments into dollars.
"I think the Fed has come to the realization that additional measures are needed in place of just deep fed funds rate cuts, though more cuts are needed," said Thomas Di Galoma, head of U.S. government bonds at Jefferies. "But the previous rate cuts had not been as effective as the Fed hoped. They found out that alleviating the stress in the financial system is needed by taking the mortgages off the books of securities dealers.
"This is a much needed step," he added. "The next stage may be set up a a government-guarantee entity like in the days of the savings-and-loan crisis to buy some of the bad mortgage assets which are not performing."
Here is the text of the Fed's statement:
Since the coordinated actions taken in December 2007, the G-10 central banks have continued to work together closelyand to consult regularly on liquidity pressures in funding markets. Pressures in some of these markets have recently increased again. We all continue to work together and will take appropriate steps to address those liquidity pressures.
To that end, today the Bank of Canada, the Bank of England, the European Central Bank, the Federal Reserve, and the Swiss National Bank are announcing specific measures.
The Federal Reserve announced today an expansion of its securities lending program. Under this new Term Securities Lending Facility (TSLF), the Federal Reserve will lend up to $200 billion of Treasury securities to primary dealers secured for a term of 28 days (rather than overnight, as in the existing program) by a pledge of other securities, including federal agency debt, federal agency residential-mortgage-backed securities (MBS), and non-agencyAAA/Aaa-rated private-label residential MBS.
The TSLF is intended to promote liquidity in the financing markets for Treasury and other collateral and thus to foster the functioning of financial markets more generally. As is the casewith the current securities lending program, securities will be made available through an auction process. Auctions will be held on a weekly basis, beginning on March 27, 2008. The Federal Reserve will consult with primary dealers on technical design features of the TSLF.
In addition, the Federal Open Market Committee has authorized increases in its existing temporary reciprocal currency arrangements (swap lines) with the European Central Bank (ECB) and the Swiss National Bank (SNB). These arrangements will now provide dollars in amounts of up to $30 billion and $6 billion to the ECB and the SNB, respectively, representing increases of $10 billion and $2 billion. The FOMC extended the term of these swap lines through September 30, 2008.
The actions announced today supplement the measures announced by the Federal Reserve on Friday to boost the size of the Term Auction Facility to $100 billion and to undertake a series of term repurchase transactions that will cumulate to $100 billion.
--Reuters and AP contributed to this story
Monday, March 10, 2008
What's Up
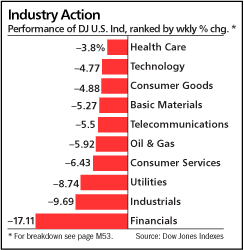
The Dow Jones Group tracks 10 different sectors and within those sectors there are 100 sub sectors. The best sub sectors follow. Only 6 sub sectors are up this year.
- Platinum and Precious Metals up 77.02%
- Gold Mining up 0.80%
- Railroads up 2.04%
- Transportation Services up 11.32%
- Trucking up 2.04%
- Oil Explorarion and Production up 2.16%
Goldilocks vs. Humpty Dumpty
Some snippets from Barrons on the worsening economic conditions.
We're in a Humpty Dumpty economy. It's broken and the Federal Reserve and Fedreral Government are trying to put the pieces back together again.
- Housing foreclosures at an all-time record high of 0.83%
- 5.8% of homeowners behind on mortgage payments, highest in two decades
- House prices fell 8.9% in 2007
- Homeowner's equity fell to 47.9% the lowest since 1945
- 101,000 private sector jobs were lost in February
We're in a Humpty Dumpty economy. It's broken and the Federal Reserve and Fedreral Government are trying to put the pieces back together again.
Friday, March 7, 2008
Boeing's Dilemma
Boeing's Air Force Tanker Bid Dilemma (from Reuters)
If it's un-American to send military contracting jobs to France, is it OK to send them to Japan? That's the question Boeing might have to answer if wrestles back a $35 billion Air Force refueling tanker contract.
The awarding of the contract last week to a European plane maker -- and not Boeing
-- has sparked outrage from union halls to the halls of Congress over the impact on U.S. jobs, prestige and national security.
But even if Chicago-based Boeing had won the deal, critical parts of its tankers would have come from other countries, including Japan and Italy. And the tankers that will be built by European Aeronautic Defence and Space and its partner, Northrop Grumman, are certain to produce jobs in the U.S.
What's more, even as Boeing supporters criticize the Air Force for outsourcing such a high-stakes award to an overseas company, Boeing itself -- along with other U.S. defense contractors -- relies on contracts from foreign governments.
"People tend to think American or foreign, black or white, but it's more gray than that," said Richard Aboulafia, an analyst with the aerospace consulting firm Teal Group. "This is an oversimplification of what is effectively a global business."
The uproar over the Air Force tanker award has taken on a protectionist tone on Capitol Hill, with many members of Congress accusing the Pentagon of choosing a French plane (EADS' Airbus subsidiary is based in France) over an American one. Leading the charge are lawmakers from Washington, Kansas and other states that stood to gain jobs from a Boeing win.
Boeing said the tanker contract would have supported 44,000 new and existing jobs at Boeing and more than 300 suppliers in more than 40 states. It would have performed much of the tanker work in Everett, Washington, and Wichita, Kansas, and used Pratt & Whitney engines built in Connecticut.
"By awarding this contract to Airbus, the U.S. government is leading those jobs to the guillotine," Washington Democrat Patty Murray said on the Senate floor Thursday.
Boeing estimates that about 85 percent of its tanker would have been made in the U.S. Still, had Boeing won the competition, its tanker would have used a fuselage made in Japan and a tail made in Italy, noted Scott Hamilton, an aviation industry consultant based outside of Seattle.
The tanker to be built by EADS and Northrop Grumman will use a fuselage from France and wings from Britain, but also General Electric Co. engines built in North Carolina and Ohio. And the plane will be assembled in Mobile, Ala. EADS and Northrop say about 60 percent of their tanker will be built in the U.S. and they project the tanker award will produce 2,000 new jobs in Mobile and support 25,000 jobs at suppliers nationwide.
"Both tankers are based on commercial airliners sold throughout the world and built from parts made throughout the world," said Loren Thompson, a defense analyst with the Lexington Institute, a think tank.
Hamilton speculated that Airbus could eventually move production of the A330 passenger plane to Mobile too, in part to take advantage of the weak dollar.
At the same time, Boeing and other big U.S. defense contractors are big suppliers to foreign governments. Boeing sells aerial refueling tankers to Japan and Italy. It sells C-17 military transport planes to the United Kingdom, Canada and Australia. And it sells F-15 fighter jets to Korea and Singapore and has sold F-15s to Japan in the past.
Roughly $27.1 billion of Boeing's total 2007 revenue of $66.4 billion came from foreign commercial and military sales. Europe alone accounted for $6.3 billion in revenue last year, with 16 percent of that coming from defense sales.
Indeed, Hamilton said, the loss of the tanker deal is not a huge one for Boeing from a corporate perspective. The contract is expected to work out to between 12 and 18 tankers a year, compared with the roughly 450 commercial aircraft that Boeing delivers annually.
The real reason for the intense anger over the Air Force decision, Hamilton believes, is that it cuts to the heart of a long-running rivalry between Boeing and Airbus.
And anti-French sentiment is compounding the furor to least some degree, with some analysts speculating that the backlash might not have been nearly so fierce had the deal gone to, say, a British company. After all, Hamilton noted, the U.K's BAE Systems is a major supplier to the Pentagon and "no one complains about that."
Setting aside the debate over jobs and tanker components, though, Aboulafia said that at least one thing is indisputable: had Boeing won the tanker contract, more of the profits from the deal would have remained inside the United States.
Thud
Associated PressUS Stocks Fall on Employment Report By TIM PARADIS 03.07.08, 8:48 AM ET
NEW YORK -
U.S. stock futures fell Friday after the government's February employment report came in weaker than expected. The Labor Department's report that employers cut jobs by 63,000 last month - the most since March 2003 - unnerved investors worried about the health of the economy and who had been expecting a 25,000 gain in jobs. While the unemployment rate fell to 4.8 percent, the decline reflects people leaving the labor force.
Dow futures fell 137, or 1.14 percent, to 11,933. S&P 500 futures fell 9.90, or 0.76 percent, to 1,298.00. The Nasdaq 100 index futures fell 3.25, or 0.19 percent, to 1,711.00.
The highly anticipated report came minutes after the Federal Reserve announced it would take fresh steps to ease credit troubles, including boosting the amount of money it will auction to banks. The move stoked worries that the employment reading would be weaker than expected.
The Fed said it will increase the size of its March 10 and 24 auctions to banks to $50 billion each. The auctions had been slated for $30 billion each and central bank officials said they plan to even bigger amounts for future auctions if need be. Also, the Fed said that it will, starting Friday, begin a series of repurchase transactions expected to reach $100 billion.
Bond prices jumped. The yield on the benchmark 10-year Treasury note, which moves opposite its price, fell to 3.51 percent from 3.59 percent late Thursday.
Light, sweet crude fell 43 cents to $105.04 per barrel in premarket electronic trading on New York Mercantile Exchange after the jobs report. A slowing economy could dampen demand for oil.
Overseas, Japan's Nikkei stock average closed down 3.27 percent after Wall Street's decline. In afternoon trading, Britain's FTSE 100 fell 0.93 percent, Germany's DAX index lost 1.24 percent, and France's CAC-40 slid 1.74 percent.
Thursday, March 6, 2008
Let's Bond
For a stable long term investment consider high quality corporate bonds. High grade corporate bonds can yield anywhere from 4-9% depending upon length of maturity and quality of the company. For example a bond from McDonalds maturing in 2018 has a coupon rate of 5.35%. No risk to principle if you keep the bond until 2018. McDonalds has little chance of ever defaulting on a bond. If you the principle before 2018 then you could lose some principle. Only buy bonds if you intend to hold them to maturity.
One more example, GE offers a bond that matures in 2017 with a coupon rate of 5.25% Again with GE there is little chance of a default. For a secure, stable return consider high grade corporate bonds.
One more example, GE offers a bond that matures in 2017 with a coupon rate of 5.25% Again with GE there is little chance of a default. For a secure, stable return consider high grade corporate bonds.
Boeing's Explanation
From Barrons
BOEING PLANS FOR AIR FORCE EXPLANATIONBoeing (BA), like Bogart in ”Casablanca,” said it was misinformed. Speaking at an investor conference Wednesday, Boeing’s defense operations chief said the company’s read of the Air Force’s request for proposals on the aerial refueling tanker - a contract that Boeing lost last week to Northrop Grumman (NOC) and the European parent of Airbus - didn’t lead Boeing to conclude the military wanted a bigger plane; the decision to go with a larger craft apparently is one of the factors that swung the gig in Northrop’s favor. Boeing called the Air Force’s choice ”puzzling,” especially since, Boeing added, it was discouraged from replacing the 767 it specified in its final proposal with the larger 777. But it will get its day in court, after a fashion: the Air Force will debrief Boeing on the contract Friday, having accelerated its timetable from the March 12 date it circled in an announcement earlier this week. For its part, Northrop has bristled at suggestions - some of them aired on the floor of Congress earlier this week - that military secrets, along with American jobs, are being exported to France. (P.S. - For anyone still puzzling over the Bogie reference: In the film, Bogart’s Rick Blaine said that he came to Casablanca for the waters. Reminded that the city was in a desert, Blaine replied, ”I was misinformed.” Here’s looking at everybody who got the reference.)
BOEING PLANS FOR AIR FORCE EXPLANATIONBoeing (BA), like Bogart in ”Casablanca,” said it was misinformed. Speaking at an investor conference Wednesday, Boeing’s defense operations chief said the company’s read of the Air Force’s request for proposals on the aerial refueling tanker - a contract that Boeing lost last week to Northrop Grumman (NOC) and the European parent of Airbus - didn’t lead Boeing to conclude the military wanted a bigger plane; the decision to go with a larger craft apparently is one of the factors that swung the gig in Northrop’s favor. Boeing called the Air Force’s choice ”puzzling,” especially since, Boeing added, it was discouraged from replacing the 767 it specified in its final proposal with the larger 777. But it will get its day in court, after a fashion: the Air Force will debrief Boeing on the contract Friday, having accelerated its timetable from the March 12 date it circled in an announcement earlier this week. For its part, Northrop has bristled at suggestions - some of them aired on the floor of Congress earlier this week - that military secrets, along with American jobs, are being exported to France. (P.S. - For anyone still puzzling over the Bogie reference: In the film, Bogart’s Rick Blaine said that he came to Casablanca for the waters. Reminded that the city was in a desert, Blaine replied, ”I was misinformed.” Here’s looking at everybody who got the reference.)
Subscribe to:
Posts (Atom)