ExxonMobil Is Best in Breed
ExxonMobil (XOM: NYSE) By Credit Suisse ($87.19, March 14, 2008)
HAVING REVIEWED THE STRATEGY presentations of the three big U.S. oils, we have concluded that ExxonMobil has the best combination of business momentum, free cash yield and capital efficiency among the group. We are upgrading the stock to an Outperform from Neutral and we are setting a $102 target price.
Our rationale for this upgrade is based partly on the recent disconnect between the performance of commodity prices and the performance of the U.S. Big Oil sector. Oil prices are well over $100 per barrel, suggesting consensus earnings forecasts for the sector need to move up in the near term.
Last week ExxonMobil disappointed some investors with an increase in capital expenditure, but we saw this as more of a mark-to-market and ExxonMobil is still the most efficient re-investor of capital in the business.
There is some inevitability to ExxonMobil's higher upstream capital expenditure: ExxonMobil is in the same industry and in many of the same projects as the other Big Oils. ExxonMobil's costs had been relatively contained in the 2005-2007 period as for projects executed in that timeframe ExxonMobil had pre-bought a significant amount of steel, had contracted drilling rigs at favorable rates and had secured some advantageous construction contracts.
As cost inflation accelerated over the last several years, we think this favorable contracting strategy, plus the underlying execution excellence of the company, had shielded ExxonMobil from the full effect of current pricing. Eventually, however, this protection wears off as older projects are completed and new projects take their place. ExxonMobil is aiming to remain at the top end of industry efficiency measures, but cost inflation finds everyone in the end.
ExxonMobil combines reasonable volume growth to 2010 with the highest operating free cash flow in the industry, and we find this attractive in the current environment. A weaker U.S. refining environment will hurt all of the Big Oils, but ExxonMobil generated only 10% of its net income in U.S. refining and marketing last year, the peak of the U.S. refining cycle, and 2008 will be under 6%.
Continued capital discipline and a focus on return on capital employed are the building blocks of ExxonMobil's high free-cash-flow generation, and the stock is currently exhibiting an attractive free-cash-flow yield, we think. ExxonMobil effectively distributed all of the free-cash-flow in 2006 and 2007 via dividends and share buybacks and at the analysts meeting it was implied that this would continue in 2008 and 2009.
A weak U.S. dollar is helping push up oil prices, and while this puts a dent in headline production volumes, the net earnings effect is positive. Big Oil equity prices have not benefited enough from the 20% increase in the oil price since February.
We think this will change in the near term, pushing up the relative performance of Big Oil versus the S&P 500, and ExxonMobil is our favorite U.S. Big Oil name to play this anticipated re-rating.
Monday, March 17, 2008


The Fed Meets Tomorrow
After this weekend's financial crisis the Fed's meeting on Tuesday takes on even more importance. The Fed is expected to cut the Fed Funds Rate from 3% to 2%.
In the United States, the federal funds rate is the interest rate at which private depository institutions (mostly banks) lend balances (federal funds) at the Federal Reserve to other depository institutions, usually overnight.[1] Changing the target rate is one form of open market operations that the Chairman of the Federal Reserve uses to regulate the supply of money in the U.S. economy.[2]
In the United States, the federal funds rate is the interest rate at which private depository institutions (mostly banks) lend balances (federal funds) at the Federal Reserve to other depository institutions, usually overnight.[1] Changing the target rate is one form of open market operations that the Chairman of the Federal Reserve uses to regulate the supply of money in the U.S. economy.[2]
Collapse Of A Bear
The collapse of Bear Stearns was rapid and deadly. The 52 week high of Bear Stearns stock was $159.36 and today is worth $2-3.00. J.P. Morgan has offered to buy out Bear Stearns for $2.00 a share for a total of $236m. As of Friday Bear Stearns was worth $3.5b. Last January (2007) Bear was worth $20b. Oh how the mighty have fallen.
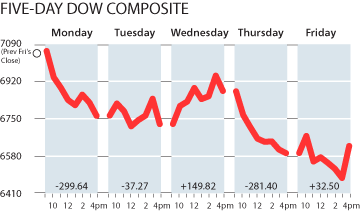
Watch the markets today and this week closely. Not where they start today but where they end on Thursday. Also note that two other major brokerages/banks report tomorrow, Goldman Sachs and Lehman Brothers, and Morgan Stanley reports on Wednesday.
To help facilitate the J.P. Morgan deal, the Federal Reserve is taking the extraordinary step of providing as much as $30 billion in financing for Bear Stearns's less-liquid assets, such as mortgage securities that the firm has been unable to sell, in what is believed to be the largest Fed advance on record to a single company. Fed officials wouldn't describe the exact financing terms or assets involved. But if those assets decline in value, the Fed would bear any loss, not J.P. Morgan.
What Is The Discount Rate/Window
The discount window is an instrument of monetary policy (usually controlled by central banks) that allows eligible institutions to borrow money from the central bank, usually on a short-term basis, to meet temporary shortages of liquidity caused by internal or external disruptions.
The interest rate charged on such loans by central bank is called the discount rate, base rate, repo rate, or primary rate. It is distinct from the federal funds rate or its equivalents in other currencies, which determine the rate at which banks lend money to each other. In recent years the discount rate has been approximately a percentage point above the federal funds rate (see Lombard credit). Because of this, it is a relatively unimportant factor in the control of the money supply, and is only taken advantage of at large volume during emergencies.
The interest rate charged on such loans by central bank is called the discount rate, base rate, repo rate, or primary rate. It is distinct from the federal funds rate or its equivalents in other currencies, which determine the rate at which banks lend money to each other. In recent years the discount rate has been approximately a percentage point above the federal funds rate (see Lombard credit). Because of this, it is a relatively unimportant factor in the control of the money supply, and is only taken advantage of at large volume during emergencies.
A Bear Week?
APFed Takes New Steps to Ease CrisisMonday March 17, 6:23 am ET By Jeannine Aversa, AP Economics Writer
Fed Takes Steps to Ease Crisis, Cuts Lending Rate to Financial Institutions to 3.25 Percent
WASHINGTON (AP) -- Worry about the damage a growing credit crisis is inflicting on an ailing U.S. economy led the Federal Reserve to make a rare weekend move, lowering a key lending rate before Wall Street opened Monday.
The central bank approved a cut in its emergency lending rate to financial institutions to 3.25 percent from 3.50 percent, effective immediately, and created a lending facility for big investment banks to secure short-term loans. The new lending facility will be available to Wall Street firms on Monday.
"These steps will provide financial institutions with greater assurance of access to funds," Federal Reserve Chairman Ben Bernanke told reporters in a brief conference call Sunday evening.
The Fed acted just after JPMorgan Chase & Co. agreed to buy rival Bear Stearns Cos. for $236.2 million in a deal that represents a stunning collapse for one of the world's largest and most venerable investment banks. Just on Friday the Fed had raced to provide emergency financing to cash-strapped Bear Stearns through JPMorgan. Days earlier the Fed announced a set of other unconventional steps to thaw out a credit market in danger of freezing shut.
"It seems as if Bernanke & Co. are pulling out all the stops to avoid a serious financial market meltdown," Richard Yamarone, an economist at Argus Research, said Sunday evening.
However on world financial markets, Asian stocks plunged Monday after the JPMorgan and Fed announcements. Markets in Australia and New Zealand were also off and European stocks fell in early trading.
Oil prices hit a record in Asian trading as the value of the dollar continued its free fall and U.S. stock index futures were down sharply, suggesting Wall Street would open lower after sinking Friday.
"There is persistent credit uncertainty. Market players have been repeatedly let down which shows the subprime mortgage problems are so deep-rooted," said Atsuji Ohara, global strategist of Shinko Securities in Tokyo.
President Bush has scheduled a White House meeting Monday afternoon with his Working Group on Financial Markets, which includes Bernanke, Treasury Secretary Henry Paulson and Securities and Exchange Commission Chairman Christopher Cox.
Paulson said Sunday, "I appreciate the additional actions taken this evening by the Federal Reserve to enhance the stability, liquidity and orderliness of our markets."
The new lending facility -- described as a cousin to the Fed's emergency lending "discount window" for banks -- is geared to give major investment houses a source of short-term cash on a regular basis -- if they need it.
It will be in place for at least six months and "may be extended as conditions warrant," the Fed said. The interest rate will be 3.25 percent and a range of collateral -- including investment-grade mortgage backed securities -- will be accepted to back the overnight loans.
The "discount" rate cut announced Sunday applies only to the short-term loans that financial institutions get directly from the Federal Reserve. It doesn't apply to individual borrowers.
The Fed's actions are the latest in a recent string of innovative steps to deal with a worsening credit crisis that has unhinged Wall Street. The action comes just two days before the central bank's scheduled meeting on Tuesday, where another big cut to a key interest rate that affects millions of people and businesses is expected to be ordered. That key rate is now at 3 percent and is expected to be cut by at least one-half percentage point on Tuesday. Analysts said the Fed's new steps may lessen pressure for a super-sized cut to that rate.
The Fed said in a statement that the steps are "designed to bolster market liquidity and promote orderly market functioning ... essential for the promotion of economic growth."
Even with the Fed's aggressive moves, economic and financial conditions keep deteriorating. An increasing number of economists believe the country already has slipped into its first recession since 2001. Many economists think that the economy is shrinking now in the January-to-March quarter. The first government figures on first-quarter economic activity will be released in late April.
The Fed on Sunday also approved the financing arrangement through which JPMorgan will acquire Bear Stearns. JPMorgan said the Fed will provide special financing for the deal. The central bank has agreed to fund up to $30 billion of Bear Stearns' less liquid assets, according to JPMorgan.
AP Business writers Joe Bel Bruno and Madlen Read contributed to this report from New York.
Friday, March 14, 2008
Humana's Medicare Part D Problem
Humana's Hurting
By Brian Orelli, Ph.D. March 13, 2008
Humana's (NYSE: HUM) chart looks like steps in the Grand Canyon that go down to the Colorado River.
A day after the health-insurance provider took a 24% drop based on WellPoint's (NYSE: WLP) reduction of its 2008 guidance, Humana dropped another 14% yesterday on news that it would nearly halve its own guidance for the first quarter.
While WellPoint blamed its woes on higher-than-expected medical costs, Humana's gloomier outlook owes to a miscalculation in setting up its Medicare prescription-drug plans.
When Humana set up the plan, the Centers for Medicare and Medicaid Services (CMS) rules required it to lower the copayments on drugs because members are allowed to pay only a certain percentage of the total costs. But the company overestimated the use of high-cost drugs, when it should have assumed that members would substitute the lower-cost drugs that require lower copayments.
By lowering the copayments on drugs, Humana shifted more of the costs onto itself. That's bad enough, but the situation gets worse. Seniors who were taking high-cost medicines and looking for a deal found one in Humana's plans, which further increased its costs.
For Humana, the good news is that the problem is limited to this year. The Medicare plans reset every year, so it'll only have to carry the high costs of the plans for the rest of 2008. Hopefully, its 2009 plan is better constructed.
For the industry, the problem appears limited to Humana. The bigger issues surrounding rising health-care costs and lower member retention could still affect other companies in the industry. While Aetna (NYSE: AET) has reaffirmed its guidance, UnitedHealth Group (NYSE: UNH) was a little wishy-washy, saying "there may be pressure on first quarter and full year 2008 results" but that it was "premature to draw adverse conclusions."
Time will tell whether the industry is entering a small valley or the Grand Canyon, but one thing's for sure: First-quarter results for health-care companies will be interesting.
The Health Of HMOs
From John Frankola
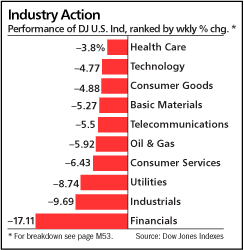
On Tuesday, WellPoint's (WLP) stock fell a whooping 28.3% as the company lowered guidance for the first quarter and full year. WellPoint reduced its EPS guidance for the first quarter to a range of $1.16 to $1.26, and its 2008 forecast to a range of $5.76 to $6.01. The mid-points of these ranges are about 16% and 8%, respectively, below WLP's previous guidance. The stock prices of other managed health care companies fell in sympathy. Aetna (AET), Coventry (CVH) and Unitedhealth (UNH) fell by 8.3%, 13.0% and 15.2%, respectively, on a day when the S&P 500 Index advanced 3.7%. WellPoint attributed the change in guidance to higher than expected medical costs, lower than expected fully insured enrollment and changing economic and regulatory environment.
Sell-side analysts were quick to reduce estimates, target prices and recommendations for WLP, as well as the other companies in the sector. On top of the reasons mentioned by the company, analysts are concerned that WellPoint's issues may signal the beginning of a cyclical downturn for the industry, which will be characterized by rising medical costs and competitive pricing. On top of these concerns, the managed care sector had already started to retreat as investors worried that a possible Democratic presidential victory could produce a more difficult regulatory environment.
From it 52-week high of 90.00 which occurred on January 8, WLP has declined 47% to its current price. It is now selling at just 8.0 times expected 2008 EPS. While sentiment has turned very negative on this sector, the current price level presents an attractive entry point for long-term investors. And while management has reduced guidance, they are still forecasting EPS growth of between 4% and 8% for 2008. (That doesn't seem like much of a cyclical downturn compared to other market sectors.)
Looking beyond the current weakness, WellPoint is well-position for long-term growth. It is the largest Blue Cross Blue Shield licensee, and with 35 million members, it is the largest managed care company in the U.S. when ranked by membership.
The managed care sector has a number of very attractive characteristics.
- There is an annuity aspect to the business - the vast majority of customers renew their coverage from year-to-year.
- After a number of years of industry consolidation, most geographic markets are now dominated by just two or three major competitors. This reduction in competition should keep pricing somewhat rational.
- The increased market share obtained industry leaders also gives the managed care companies more clout when negotiating fees paid for products and services.
- The size and scale which most companies have achieved present a barrier to entry for new competitors.
- With concern over rapidly rising healthcare costs, the managed care companies have strategically positioned themselves to be part of the healthcare cost solution. These companies realize their future success will depend on helping to control costs by forcing healthcare providers to be more efficient, providing products that give their members market incentives to control costs, and by making better use of information.
- Despite the current concern over a possible cyclical downturn, companies in this sector have historically demonstrated a high level of earnings and cash flow stability.
With the long-term fundamentals intact and a price/earnings ratio that is almost half that of the market, WLP looks to be a great value for long-term investors.
With the entire sector getting crushed in the wake of WellPoint's announcement, Aetna, Coventry and Unitedhealth also look attractive at current levels. All have a price/earnings ratio of 11 or less on 2008 EPS estimates. Aetna reiterated it guidance for 2008 this week, yet is trading 25% below its 52-week high. Coventry (down 31% from its 52-week high) could be an acquisition candidate at current price levels.
Its market cap is just $7 billion, compared to $21 billion, $47 billion and $26 billion, respectively, for Aetna, Unitedhealth and WellPoint. Unitedhealth (off 36% from its 52-week high) is the largest managed care company in terms of revenue and has the most diversified suite of products and services. Unitedhealth also made an announcement this week, recognizing some of the market's concerns, but stopping short of changing guidance.
Disclosure: Author owns a position in AET, CVH and WLP and manages accounts which hold AET, CVH, UNH and WLP.
Thursday, March 13, 2008
Duh
Store sales suffer big stumble
Retail sales were much worse than expected in February, a sign that consumers are cutting back.
By Parija B. Kavilanz, CNNMoney.com senior writer
Last Updated: March 13, 2008: 8:41 AM EDT
Monthly retail sales suffered a surprising drop last month as American households continued to curtail their spending amid higher energy and food prices and a weakening jobs market.
The Commerce Department reported Thursday that total retail sales fell 0.6%, compared to a revised 0.4% increase in January. January sales were originally reported to have increased 0.3%
Economists surveyed by Briefing.com expected a 0.2% gain in retail sales for the month.
Stripping out volatile auto sales, sales fell 0.2% compared to a revised 0.5% gain in January. January sales, excluding autos, were originally reported to have increased 0.3%.
Economists had anticipated a 0.2% gain in the measure.
Target Raising Cash
From Todd Sullivan -
This looks like another activist victory for Bill Ackman.It is being reported that Target (TGT) is currently in talks to sell 1/2 it credit card business. Details are not forthcoming at this time. The sale is expected to net $4 billion which could repurchase almost 10% of outstanding shares at today's prices. The move is a good one considering the deterioration in quality of the portfolio and will enable the company to repurchase shares to keep EPS growing to satisfy investors, even if the actual net income line does not grow that fast.
This looks like another activist victory for Bill Ackman.It is being reported that Target (TGT) is currently in talks to sell 1/2 it credit card business. Details are not forthcoming at this time. The sale is expected to net $4 billion which could repurchase almost 10% of outstanding shares at today's prices. The move is a good one considering the deterioration in quality of the portfolio and will enable the company to repurchase shares to keep EPS growing to satisfy investors, even if the actual net income line does not grow that fast.
Wednesday, March 12, 2008
Gee - no GE!
From Ockham Research
General Electric (GE) stock has underperformed versus the Dow and the S&P 500 over the last five years, but it is now showing signs of improvement. GE is making the effort to further diversify as its Energy Financial Services unit has plans to invest more than 5 times its normal 3 year investment in overseas development, some $5 billion. This is a wise move for the already multifaceted company that sells a wide range of products from appliances to ultrasound equipment. However, the significant news of today is all about their energy infrastructure sales in emerging markets in Asia, Latin America, and the Middle East.
Emerging markets such as these have been growing quite rapidly and their infrastructure spending simply has not kept pace. The Asian Development Bank estimates that there is a need in the next 10 years for over $3 trillion in roads, energy projects, ports, and sanitation. Current investment trends suggest that infrastructure investment could fall short of that estimate by half. Energy infrastructure expenditures in emerging markets is one way that GE is hoping to offset weakness from domestic sales as the U.S. economy continues to slow. Thus, GE is jumping at the opportunity to assist emerging economies mostly with energy and water projects.
However, GE is also at the forefront of the rapidly growing wind power industry, as evidenced by a $1 billion deal to build a wind turbine in the United States, its second such contract in recent months. Out of all U.S. energy producing projects completed during 2007, wind power accounted for about 30%.
General Electric is trending towards a more global business model, as last year was the first year in GE’s history in which more than half of their revenue was from sales outside of the U.S. The ramp up of GE’s Energy unit to focus on emerging markets is just one of the ways that GE is working globally.
Since U.S. consumer sentiment is weak, it appears that this strategy shift could not have come at a better time. We have little reason to question the prudence of GE management in making such a leap. Management also achieved a fairly high 19.2% return-on-equity [ROE] at last reporting. Based on the Ockham Research methodology, we believe that GE’s price-to-sales is about a third lower than we would normally expect given historical ranges. Furthermore, we would expect to see price-to-cash flow in the range of 12.1 to 16.3, but this valuation metric is also fairly low at only 9.2 times. As such, patient investors should consider purchasing GE shares in the low thirties.
Subscribe to:
Posts (Atom)