PRODUCTIVITY AND COSTS First Quarter 2008, Revised
The Bureau of Labor Statistics of the U.S. Department of Labor today reported revised productivity data--as measured by output per hour of all persons--for the first quarter of 2008. The revised seasonally adjusted annual rates of productivity change in the first quarter were:
2.4 percent in the business sector and
2.6 percent in the nonfarm business sector
In both sectors, the first-quarter productivity gains were greater than the preliminary estimates reported on May 7, due primarily to upward revisions to output growth.
Continued strong productivity growth helps keep inflation in check in the face of rising oil and commodity prices, and accommodates moderate wage growth. (Tim)
Wednesday, June 4, 2008


May's ADP National Employment Report

The ADP National Employment Report
May, 2008
Summary
May, 2008
Summary
Nonfarm private employment increased 40,000 from April to May 2008 on a seasonally adjusted basis, according to the ADP National Employment ReportTM. The estimated change in employment from March to April was revised up from an increase of 10,000 to an increase of 13,000. Though May’s estimate for a moderate increase in employment is above consensus forecasts of an outright decline, it nevertheless suggests continued weakness in employment.
Details
Nonfarm private employment increased 40,000 from April to May 2008 on a seasonally
adjusted basis, according to the ADP National Employment Report™. The estimated
change in employment from March to April was revised up from an increase of 10,000 to
an increase of 13,000.
Though May’s estimate for a moderate increase in employment is above consensus
forecasts of an outright decline, it nevertheless suggests continued weakness in
employment.
Employment in the service-providing sector of the economy grew 77,000, while
employment in the goods-producing sector declined 37,000, the eighteenth consecutive
monthly decline. Manufacturing employment fell 26,000 in May and marked the twentyfirst
consecutive monthly decline.
Large businesses, defined as those with 500 or more workers, saw employment decline
18,000, while medium-size companies with between 50 and 499 workers declined by
3,000. Conversely, employment among small-size businesses, defined as those with
fewer than 50 workers, advanced 61,000 during the month.
Two sectors of the economy hit hardest by recent problems in mortgage markets have
been residential construction and financial activities related to home sales and mortgage
lending. In May, construction employment dropped 13,000. This was the eighteenth
consecutive monthly decline, and brings the total decline in construction jobs since the
peak in August of 2006 to 298,000. However, May’s decline was the smallest since
January. In addition, employment in financial activities advanced 5,000 during May, the
third consecutive monthly gain.
Nonfarm private employment increased 40,000 from April to May 2008 on a seasonally
adjusted basis, according to the ADP National Employment Report™. The estimated
change in employment from March to April was revised up from an increase of 10,000 to
an increase of 13,000.
Though May’s estimate for a moderate increase in employment is above consensus
forecasts of an outright decline, it nevertheless suggests continued weakness in
employment.
Employment in the service-providing sector of the economy grew 77,000, while
employment in the goods-producing sector declined 37,000, the eighteenth consecutive
monthly decline. Manufacturing employment fell 26,000 in May and marked the twentyfirst
consecutive monthly decline.
Large businesses, defined as those with 500 or more workers, saw employment decline
18,000, while medium-size companies with between 50 and 499 workers declined by
3,000. Conversely, employment among small-size businesses, defined as those with
fewer than 50 workers, advanced 61,000 during the month.
Two sectors of the economy hit hardest by recent problems in mortgage markets have
been residential construction and financial activities related to home sales and mortgage
lending. In May, construction employment dropped 13,000. This was the eighteenth
consecutive monthly decline, and brings the total decline in construction jobs since the
peak in August of 2006 to 298,000. However, May’s decline was the smallest since
January. In addition, employment in financial activities advanced 5,000 during May, the
third consecutive monthly gain.
Tuesday, June 3, 2008
Factory Orders For April 2008

Summary
New orders for manufactured goods in April, up two consecutive months, increased $5.0 billion or 1.1 percent to $445.2 billion, the U.S. Census Bureau reported today. This followed a 1.5 percent March increase. Shipments, up three of the last four months, increased $9.6 billion or 2.2 percent to $443.9 billion. This was at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.1 percent March increase. Unfilled orders, up twenty-six of the last twenty-seven months, increased $7.3 billion or 0.9 percent to $804.4 billion. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.3 percent March increase. The unfilled orders-to- shipments ratio was 5.29, down from 5.30 in March. Inventories, down slightly following seven consecutive monthly increases, decreased $0.1 billion to $545.7 billion. This followed a 0.9 percent March increase. The inventories-to-shipments ratio was 1.23, down from 1.26 in March.
New Orders
New orders for manufactured durable goods in April, down three of the last four months, decreased $1.2 billion or 0.6 percent to $214.4 billion, revised from the previously published 0.5 percent decrease. This followed a 0.2 percent March decrease.
New orders for manufactured nondurable goods increased $6.2 billion or 2.8 percent to $230.8 billion.
Shipments
Shipments of manufactured durable goods in April, up following two consecutive monthly decreases, increased $3.4 billion or 1.6 percent to $213.1 billion, revised from the previously published 1.2 percent increase. This followed a 0.9 percent March decrease.
Shipments of manufactured nondurable goods, up two consecutive months, increased $6.2 billion or 2.8 percent to $230.8 billion. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 3.1 percent March increase. This increase was led by petroleum and coal products, which increased $3.6 billion or 6.2 percent to $62.0 billion. Petroleum and coal products was also at the highest level since the series was first stated on a NAICS basis in 1992.
Unfilled Orders
Unfilled orders for manufactured durable goods in April, up twenty-six of the last twenty-seven months, increased $7.3 billion or 0.9 percent to $804.4 billion, revised from the previously published 1.0 percent increase. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.3 percent March increase.
Inventories
Inventories of manufactured durable goods in April, up nine of the last ten months, increased $2.0 billion or 0.6 percent to $329.1 billion, revised from the previously published 0.5 percent increase. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.0 percent March increase.
Inventories of manufactured nondurable goods, down following five consecutive monthly increases, decreased $2.1 billion or 1.0 percent to $216.6 billion. This followed a 0.9 percent March increase. Petroleum and coal products drove the decrease, down $2.6 billion or 6.4 percent to $38.9 billion.
By stage of fabrication, April materials and supplies increased 0.6 percent in durable goods and decreased 0.1 percent in nondurable goods. Work in process increased 1.3 percent in durable goods and decreased 3.2 percent in nondurable goods. Finished goods decreased 0.2 percent in durable goods and 0.7 percent in nondurable goods.
New orders for manufactured goods in April, up two consecutive months, increased $5.0 billion or 1.1 percent to $445.2 billion, the U.S. Census Bureau reported today. This followed a 1.5 percent March increase. Shipments, up three of the last four months, increased $9.6 billion or 2.2 percent to $443.9 billion. This was at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.1 percent March increase. Unfilled orders, up twenty-six of the last twenty-seven months, increased $7.3 billion or 0.9 percent to $804.4 billion. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.3 percent March increase. The unfilled orders-to- shipments ratio was 5.29, down from 5.30 in March. Inventories, down slightly following seven consecutive monthly increases, decreased $0.1 billion to $545.7 billion. This followed a 0.9 percent March increase. The inventories-to-shipments ratio was 1.23, down from 1.26 in March.
New Orders
New orders for manufactured durable goods in April, down three of the last four months, decreased $1.2 billion or 0.6 percent to $214.4 billion, revised from the previously published 0.5 percent decrease. This followed a 0.2 percent March decrease.
New orders for manufactured nondurable goods increased $6.2 billion or 2.8 percent to $230.8 billion.
Shipments
Shipments of manufactured durable goods in April, up following two consecutive monthly decreases, increased $3.4 billion or 1.6 percent to $213.1 billion, revised from the previously published 1.2 percent increase. This followed a 0.9 percent March decrease.
Shipments of manufactured nondurable goods, up two consecutive months, increased $6.2 billion or 2.8 percent to $230.8 billion. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 3.1 percent March increase. This increase was led by petroleum and coal products, which increased $3.6 billion or 6.2 percent to $62.0 billion. Petroleum and coal products was also at the highest level since the series was first stated on a NAICS basis in 1992.
Unfilled Orders
Unfilled orders for manufactured durable goods in April, up twenty-six of the last twenty-seven months, increased $7.3 billion or 0.9 percent to $804.4 billion, revised from the previously published 1.0 percent increase. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.3 percent March increase.
Inventories
Inventories of manufactured durable goods in April, up nine of the last ten months, increased $2.0 billion or 0.6 percent to $329.1 billion, revised from the previously published 0.5 percent increase. This was also at the highest level since the series was first stated on a NAICS basis in 1992 and followed a 1.0 percent March increase.
Inventories of manufactured nondurable goods, down following five consecutive monthly increases, decreased $2.1 billion or 1.0 percent to $216.6 billion. This followed a 0.9 percent March increase. Petroleum and coal products drove the decrease, down $2.6 billion or 6.4 percent to $38.9 billion.
By stage of fabrication, April materials and supplies increased 0.6 percent in durable goods and decreased 0.1 percent in nondurable goods. Work in process increased 1.3 percent in durable goods and decreased 3.2 percent in nondurable goods. Finished goods decreased 0.2 percent in durable goods and 0.7 percent in nondurable goods.
ValueLine 2011-13 Projection for GM
GM's new initiatives toward more fuel efficient hybrids and a reduction in production of trucks and SUVs makes GM a very good long term investment strategy. GM's stock price has recently slid into the $17.00 range. (Tim)
2011-2013 ValueLine projections are:
-----------Price-----------Gain------Annual Total Return
High------$50.00-------(+150%)----------28%
Low-------$35.00-------(+75%)-----------18%
2011-2013 ValueLine projections are:
-----------Price-----------Gain------Annual Total Return
High------$50.00-------(+150%)----------28%
Low-------$35.00-------(+75%)-----------18%
Top 10 Sub-Sectors
The ten leading market groups in the ten Dow Jones sub-sectors for 2008 are:
1) Platinum and Precious Metals--48.55%
2) Coal--------------------------43.06%
3) Railroads----------------------38.25%
4) Transportation Services-------34.50%
5) Steel-------------------------28.65%
6) Trucking---------------------21.98%
7) Oil Exploration&Production-----19.37%
8) Computer Services------------15.09%
9) Oil Equipment&Services--------13.28%
10) Waste&Disposal Services-----9.84%
1) Platinum and Precious Metals--48.55%
2) Coal--------------------------43.06%
3) Railroads----------------------38.25%
4) Transportation Services-------34.50%
5) Steel-------------------------28.65%
6) Trucking---------------------21.98%
7) Oil Exploration&Production-----19.37%
8) Computer Services------------15.09%
9) Oil Equipment&Services--------13.28%
10) Waste&Disposal Services-----9.84%
GM's New Direction

GM Announces New Products, Capacity Adjustments; Continues Transformation of North American Business
New car, powertrain programs to meet the changing needs of U.S. customers
Chevy Volt production gets the green light from the GM board
GM builds on car momentum with additional capacity; adjusts truck capacity
Hummer brand set for strategic review
WILMINGTON, Del. - GM today announced a range of strategic initiatives to aggressively respond to growing demand for fuel-efficient vehicles and to economic and market challenges in North America. Rick Wagoner, GM chairman and CEO, made the announcements here as part of the GM annual meeting of stockholders.
Major initiatives announced by Wagoner include:
A new global compact car program for Chevrolet, a next generation for the popular Chevy Aveo, and a high efficiency engine module for the U.S. market.
Funding for production of the Chevy Volt extended-range electric vehicle.
Addition of third shifts to Lordstown and Orion, which build hot-selling Chevy and Pontiac cars.
Cessation of production at four plants that build pickups, SUVs and medium-duty trucks.
A strategic review of the Hummer brand.
"From the start of our North American turnaround plan in 2005, I've said that our goal is not just to return GM to profitability, but to structure GM globally for sustained profitability and growth," said Wagoner.
"Since the first of this year, however, U.S. economic and market conditions have become significantly more difficult," he said. "Higher gasoline prices are changing consumer behavior, and they are significantly affecting the U.S. auto industry sales mix."
In North America, GM has been moving rapidly and successfully to revitalize its car lineup and grow its crossover business. New GM cars and crossovers, including the Cadillac CTS, Chevy Malibu, Pontiac Vibe and Buick Enclave, have been selling strongly, and GM intends to build on this success. In fact, 18 of the next 19 new GM products for the U.S. will be cars or crossovers.
Additional operational and strategic actions will be required to position GM for sustainable profitability and growth. These initiatives fall into three broad areas: product and technology, manufacturing facilities and capacity, and the Hummer brand.
New Chevrolet models and a high-efficiency engine module approved
To further strengthen GM's lineup of fuel-efficient cars, the GM board has approved a next-generation compact Chevy for the U.S. and global markets, a next generation of the popular Chevy Aveo, and a U.S. production module of GM's 1.4-liter turbocharged four-cylinder engine.
The new Chevy compact will be better equipped than today's compact cars, and will be designed to set quality and safety benchmarks for the compact class. Production will begin in mid-2010 at GM's Lordstown, Ohio, plant, subject to final negotiations with state and local authorities.
"This car will represent the first U.S. application of our global architecture strategy," said Wagoner. "This strategy will pay major dividends as we leverage our extensive car product development capability in Europe, Korea, and other locations to accelerate the shift in our U.S. product portfolio."
The next-generation compact will be pure Chevrolet in design, and will feature the 1.4-liter turbocharged version of GM's global four-cylinder engine. With this engine and a manual transmission, the new Chevy is expected to achieve a 9 mpg improvement over Chevy's current entry in this segment. The engine will be produced in Flint, Michigan, again subject to final negotiations with state and local authorities.
Also recently approved was a next generation of the popular Chevy Aveo. Based on a global architecture, the Aveo is also expected to have segment-leading fuel economy when it goes on sale in the U.S. market in the second half of 2010.
These new Chevy models will help build on GM's leadership in fuel efficient vehicles. For example, GM continues to offer more vehicles with a 30-mpg or better highway fuel economy rating than any competitor.
Chevy Volt is a go
The Chevy Volt took a major step toward the showroom with formal approval by the GM board of funding for production of the extended-range electric vehicle. This approval, which includes funding for production development and tooling, indicates that GM leadership believes that the technology for the Volt, including its lithium-ion batteries, will be ready for volume production on schedule.
"The Chevy Volt is a go," said Wagoner. "We believe this is the biggest step yet in our industry's move away from our historic, virtually complete reliance on petroleum to power vehicles."
"We intend to show a production version of the Chevy Volt publicly in the very near future, and we remain focused on our target of getting the Volt into Chevrolet showrooms by the end of 2010," Wagoner said.
Preliminary plans are to produce the Volt at GM's Detroit-Hamtramck Assembly Center, subject to successful discussions with state and local governments.
Capacity adjustments address market shifts
GM will react to the shift in the U.S. market by increasing production of small and midsize cars and reducing production of pickups and truck-based SUVs.
GM will add a third shift in September to the Orion Assembly Center in Michigan, which builds the hot-selling Chevy Malibu and Pontiac G6. Also in September, the company plans to add a third shift at Lordstown Car Assembly in Ohio, which builds the Chevy Cobalt and Pontiac G5.
On the other side of the mix equation, market-related declines in truck sales mean that, over time, GM will cease production at four truck plants.
Oshawa Truck Assembly in Canada, which builds the Chevy Silverado and GMC Sierra, will likely cease production in 2009, while Moraine, Ohio, which builds the Chevy TrailBlazer, GMC Envoy and Saab 9-7x, will end production at the end of the 2010 model run, or sooner, if demand dictates. Janesville, Wisconsin, will cease production of medium-duty trucks by the end of 2009, and of the Tahoe, Suburban and Yukon in 2010, or sooner, if market demand dictates. Chevrolet Kodiak medium-duty truck production will also end in Toluca, Mexico, by the end of this year.
GM expects that these actions, along with the recent announcement to remove shifts at two other U.S. truck plants (Pontiac and Flint, Michigan), will result in an additional GM North America structural cost savings of more than $1 billion, on a running rate basis, by 2010. This is on top of the approximately $5 billion running rate reduction by 2011 that we announced earlier this year, and also in addition to the $9 billion reduction accomplished over the 2006-07 period in North America.
GM will work closely with its union partners to mitigate the impact of these difficult actions, which are made necessary by long-term changes in consumer demand for trucks and SUVs.
Strategic assessment for Hummer brand
Finally, GM is undertaking a strategic review of the Hummer brand to determine its fit within the GM portfolio. At this point, the company is considering all options, from a complete revamp of the product lineup to a partial or complete sale of the brand.
Moving forward
"We are making a number of important announcements today, covering everything from product and technology investments to capacity adjustments to a strategic review of our Hummer brand," said Wagoner. "These moves are all in response to the rapid rise in oil prices and the resulting changes in the U.S., changes that we believe are more structural than cyclical.
"While some of the actions, especially the capacity reductions, are very difficult, they are necessary to adjust to changing market and economic conditions and to keep GM's U.S. turnaround on track and moving forward."
New car, powertrain programs to meet the changing needs of U.S. customers
Chevy Volt production gets the green light from the GM board
GM builds on car momentum with additional capacity; adjusts truck capacity
Hummer brand set for strategic review
WILMINGTON, Del. - GM today announced a range of strategic initiatives to aggressively respond to growing demand for fuel-efficient vehicles and to economic and market challenges in North America. Rick Wagoner, GM chairman and CEO, made the announcements here as part of the GM annual meeting of stockholders.
Major initiatives announced by Wagoner include:
A new global compact car program for Chevrolet, a next generation for the popular Chevy Aveo, and a high efficiency engine module for the U.S. market.
Funding for production of the Chevy Volt extended-range electric vehicle.
Addition of third shifts to Lordstown and Orion, which build hot-selling Chevy and Pontiac cars.
Cessation of production at four plants that build pickups, SUVs and medium-duty trucks.
A strategic review of the Hummer brand.
"From the start of our North American turnaround plan in 2005, I've said that our goal is not just to return GM to profitability, but to structure GM globally for sustained profitability and growth," said Wagoner.
"Since the first of this year, however, U.S. economic and market conditions have become significantly more difficult," he said. "Higher gasoline prices are changing consumer behavior, and they are significantly affecting the U.S. auto industry sales mix."
In North America, GM has been moving rapidly and successfully to revitalize its car lineup and grow its crossover business. New GM cars and crossovers, including the Cadillac CTS, Chevy Malibu, Pontiac Vibe and Buick Enclave, have been selling strongly, and GM intends to build on this success. In fact, 18 of the next 19 new GM products for the U.S. will be cars or crossovers.
Additional operational and strategic actions will be required to position GM for sustainable profitability and growth. These initiatives fall into three broad areas: product and technology, manufacturing facilities and capacity, and the Hummer brand.
New Chevrolet models and a high-efficiency engine module approved
To further strengthen GM's lineup of fuel-efficient cars, the GM board has approved a next-generation compact Chevy for the U.S. and global markets, a next generation of the popular Chevy Aveo, and a U.S. production module of GM's 1.4-liter turbocharged four-cylinder engine.
The new Chevy compact will be better equipped than today's compact cars, and will be designed to set quality and safety benchmarks for the compact class. Production will begin in mid-2010 at GM's Lordstown, Ohio, plant, subject to final negotiations with state and local authorities.
"This car will represent the first U.S. application of our global architecture strategy," said Wagoner. "This strategy will pay major dividends as we leverage our extensive car product development capability in Europe, Korea, and other locations to accelerate the shift in our U.S. product portfolio."
The next-generation compact will be pure Chevrolet in design, and will feature the 1.4-liter turbocharged version of GM's global four-cylinder engine. With this engine and a manual transmission, the new Chevy is expected to achieve a 9 mpg improvement over Chevy's current entry in this segment. The engine will be produced in Flint, Michigan, again subject to final negotiations with state and local authorities.
Also recently approved was a next generation of the popular Chevy Aveo. Based on a global architecture, the Aveo is also expected to have segment-leading fuel economy when it goes on sale in the U.S. market in the second half of 2010.
These new Chevy models will help build on GM's leadership in fuel efficient vehicles. For example, GM continues to offer more vehicles with a 30-mpg or better highway fuel economy rating than any competitor.
Chevy Volt is a go
The Chevy Volt took a major step toward the showroom with formal approval by the GM board of funding for production of the extended-range electric vehicle. This approval, which includes funding for production development and tooling, indicates that GM leadership believes that the technology for the Volt, including its lithium-ion batteries, will be ready for volume production on schedule.
"The Chevy Volt is a go," said Wagoner. "We believe this is the biggest step yet in our industry's move away from our historic, virtually complete reliance on petroleum to power vehicles."
"We intend to show a production version of the Chevy Volt publicly in the very near future, and we remain focused on our target of getting the Volt into Chevrolet showrooms by the end of 2010," Wagoner said.
Preliminary plans are to produce the Volt at GM's Detroit-Hamtramck Assembly Center, subject to successful discussions with state and local governments.
Capacity adjustments address market shifts
GM will react to the shift in the U.S. market by increasing production of small and midsize cars and reducing production of pickups and truck-based SUVs.
GM will add a third shift in September to the Orion Assembly Center in Michigan, which builds the hot-selling Chevy Malibu and Pontiac G6. Also in September, the company plans to add a third shift at Lordstown Car Assembly in Ohio, which builds the Chevy Cobalt and Pontiac G5.
On the other side of the mix equation, market-related declines in truck sales mean that, over time, GM will cease production at four truck plants.
Oshawa Truck Assembly in Canada, which builds the Chevy Silverado and GMC Sierra, will likely cease production in 2009, while Moraine, Ohio, which builds the Chevy TrailBlazer, GMC Envoy and Saab 9-7x, will end production at the end of the 2010 model run, or sooner, if demand dictates. Janesville, Wisconsin, will cease production of medium-duty trucks by the end of 2009, and of the Tahoe, Suburban and Yukon in 2010, or sooner, if market demand dictates. Chevrolet Kodiak medium-duty truck production will also end in Toluca, Mexico, by the end of this year.
GM expects that these actions, along with the recent announcement to remove shifts at two other U.S. truck plants (Pontiac and Flint, Michigan), will result in an additional GM North America structural cost savings of more than $1 billion, on a running rate basis, by 2010. This is on top of the approximately $5 billion running rate reduction by 2011 that we announced earlier this year, and also in addition to the $9 billion reduction accomplished over the 2006-07 period in North America.
GM will work closely with its union partners to mitigate the impact of these difficult actions, which are made necessary by long-term changes in consumer demand for trucks and SUVs.
Strategic assessment for Hummer brand
Finally, GM is undertaking a strategic review of the Hummer brand to determine its fit within the GM portfolio. At this point, the company is considering all options, from a complete revamp of the product lineup to a partial or complete sale of the brand.
Moving forward
"We are making a number of important announcements today, covering everything from product and technology investments to capacity adjustments to a strategic review of our Hummer brand," said Wagoner. "These moves are all in response to the rapid rise in oil prices and the resulting changes in the U.S., changes that we believe are more structural than cyclical.
"While some of the actions, especially the capacity reductions, are very difficult, they are necessary to adjust to changing market and economic conditions and to keep GM's U.S. turnaround on track and moving forward."
Monday, June 2, 2008
AT&T Valueline Outlook
AT&T Inc.’s operating environment appears to be getting chillier. Though the wireless and corporate/business units continue to perform well in the current climate, the telecom company’s traditional, consumer-oriented phone division is being adversely affected by the slowdown in the
U.S. economy. In fact, access-line losses have accelerated lately (the line base contracted a greater-than-expected 7.4% on a year-over-year basis during the fourth quarter), due to an uptick in nonpayment rates and service disconnections. This, coupled with heightened competition from wireless carriers and cable VoIP providers, is taking a toll on once-core wireline voice revenues.
In the meantime . . . Pricing within the wireless arena is softening, as the major service providers
aggressively look to shore up their customer bases. In an industry-transforming move, AT&T, Verizon, and T-Mobile recently introduced rival, $99.99-a-month unlimited calling plans. This decision will, we think, ultimately put pressure on most carriers’ results. And the new pricing
plans will probably lead to further rate cuts down the road.
That said . . . We believe that the company will remain in a growth mode over the next few ears. Although prices seem to be coming down, AT&T’s mobility business is still thriving, thanks to share advances (mostly at the expense of Sprint) and the success of Apple’s iPhone. (The company is the exclusive U.S. carrier for the revolutionary handset.) Moreover, broadband
penetration levels continue to rise. And the firm’s new premium, Internet Protocol based
TV service, U-verse, is quickly gaining traction in the marketplace. Indeed, management expects the service, which is meant to compete with Verizon’s FiOS offering and cable operators’ all-in-one packages, to have more than one million subscribers by the end of 2008.
At the current quotation, this highprofile issue has appeal as both a short- and long-term olding. Despite worsening business conditions, AT&T has enough growth drivers in place to support
healthy profit increases in 2008 and beyond. What’s more, the company continues to pay a generous dividend, which should please income-oriented investors.
Justin Hellman March 28, 2008 (Valueline)
U.S. economy. In fact, access-line losses have accelerated lately (the line base contracted a greater-than-expected 7.4% on a year-over-year basis during the fourth quarter), due to an uptick in nonpayment rates and service disconnections. This, coupled with heightened competition from wireless carriers and cable VoIP providers, is taking a toll on once-core wireline voice revenues.
In the meantime . . . Pricing within the wireless arena is softening, as the major service providers
aggressively look to shore up their customer bases. In an industry-transforming move, AT&T, Verizon, and T-Mobile recently introduced rival, $99.99-a-month unlimited calling plans. This decision will, we think, ultimately put pressure on most carriers’ results. And the new pricing
plans will probably lead to further rate cuts down the road.
That said . . . We believe that the company will remain in a growth mode over the next few ears. Although prices seem to be coming down, AT&T’s mobility business is still thriving, thanks to share advances (mostly at the expense of Sprint) and the success of Apple’s iPhone. (The company is the exclusive U.S. carrier for the revolutionary handset.) Moreover, broadband
penetration levels continue to rise. And the firm’s new premium, Internet Protocol based
TV service, U-verse, is quickly gaining traction in the marketplace. Indeed, management expects the service, which is meant to compete with Verizon’s FiOS offering and cable operators’ all-in-one packages, to have more than one million subscribers by the end of 2008.
At the current quotation, this highprofile issue has appeal as both a short- and long-term olding. Despite worsening business conditions, AT&T has enough growth drivers in place to support
healthy profit increases in 2008 and beyond. What’s more, the company continues to pay a generous dividend, which should please income-oriented investors.
Justin Hellman March 28, 2008 (Valueline)
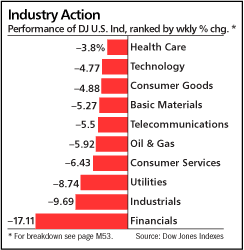
2008 YTD Sector Performance
The ten Dow Jones market industry groups performance for 2008 are:
1) Basic Materials------ +11.17%
2) Consumer Goods----- -5.09%
3) Consumer Services--- -1.60%
4) Financials----------- -13.00%
5) Health Care---------- -8.59
6) Industrials----------- -0.54%
7) Oil&Gas-------------- +7.30%
8) Technology----------- -4.27%
9) Telecommunications-- -8.01%
10) Utilities-------------- -2.34%
1) Basic Materials------ +11.17%
2) Consumer Goods----- -5.09%
3) Consumer Services--- -1.60%
4) Financials----------- -13.00%
5) Health Care---------- -8.59
6) Industrials----------- -0.54%
7) Oil&Gas-------------- +7.30%
8) Technology----------- -4.27%
9) Telecommunications-- -8.01%
10) Utilities-------------- -2.34%
The Week Ahead

Market Movers -
June 3 - Factory Orders
June 5 - Initial Unemployment Claims
June 6 - Employment Situation
GE A Good Bet
From Barrons
GENERAL ELECTRIC, AT 30.76, closed Friday with a dividend yield of 4.03%. The 10-year Treasury yield was 4.05%. General Electric (ticker: GE) is rated triple-A, rightly. The U.S. government implicitly is rated triple-A, and retains this halo strictly for its taxing authority. GE's yield will grow; your bonds' won't.
Until the past few months, GE's yield has been equal to or below the Treasury yield only once, in early 2003, right before GE's shares and the stock market took off. Maybe this isn't enough to make GE a ripping Buy (identifiable catalysts are few), but it suggests the downside is limited and the shares finally are out of favor enough, after the company's clanging earnings miss last quarter, to improve their risk/reward equation.
At below 14 times expected earnings, GE -- composed of roughly 45% infrastructure/industrial profits, 35% financial, 11% media and 9% health care -- trades in line with a like blend of industry-comparable multiples, based on a back-of-the-envelope reckoning. In other words, an investor at long last need not assume that GE's businesses are above-average -- as, in most cases, they certainly are -- to justify buying the stock.
CEO Jeffrey Immelt admirably turned the other cheek to his predecessor's recent public chiding, when he could have pointed out that former CEO Jack Welch's reputation and personal wealth were swollen beyond calculation by the stock market's general valuation inflation during his tenure. More important, Immelt continues to buy GE shares in the open market, $3.5 million just last week.
GENERAL ELECTRIC, AT 30.76, closed Friday with a dividend yield of 4.03%. The 10-year Treasury yield was 4.05%. General Electric (ticker: GE) is rated triple-A, rightly. The U.S. government implicitly is rated triple-A, and retains this halo strictly for its taxing authority. GE's yield will grow; your bonds' won't.
Until the past few months, GE's yield has been equal to or below the Treasury yield only once, in early 2003, right before GE's shares and the stock market took off. Maybe this isn't enough to make GE a ripping Buy (identifiable catalysts are few), but it suggests the downside is limited and the shares finally are out of favor enough, after the company's clanging earnings miss last quarter, to improve their risk/reward equation.
At below 14 times expected earnings, GE -- composed of roughly 45% infrastructure/industrial profits, 35% financial, 11% media and 9% health care -- trades in line with a like blend of industry-comparable multiples, based on a back-of-the-envelope reckoning. In other words, an investor at long last need not assume that GE's businesses are above-average -- as, in most cases, they certainly are -- to justify buying the stock.
CEO Jeffrey Immelt admirably turned the other cheek to his predecessor's recent public chiding, when he could have pointed out that former CEO Jack Welch's reputation and personal wealth were swollen beyond calculation by the stock market's general valuation inflation during his tenure. More important, Immelt continues to buy GE shares in the open market, $3.5 million just last week.
Subscribe to:
Posts (Atom)